
Inventory Discounts and Rebates: Key PFRS Accounting Considerations
Summary
This accounting alert highlights the PFRS Viewpoint released to discuss the purchaser's accounting treatment for various types of inventory discounts and rebates, including trade discounts, settlement discounts, volume-based rebates, and other supplier payment arrangements. The publication provides guidance on the application of PAS 2 Inventories, PFRS 15 Revenue from Contracts with Customers, and PFRS 18 Presentation and Disclosure in Financial Statements.
Key Points
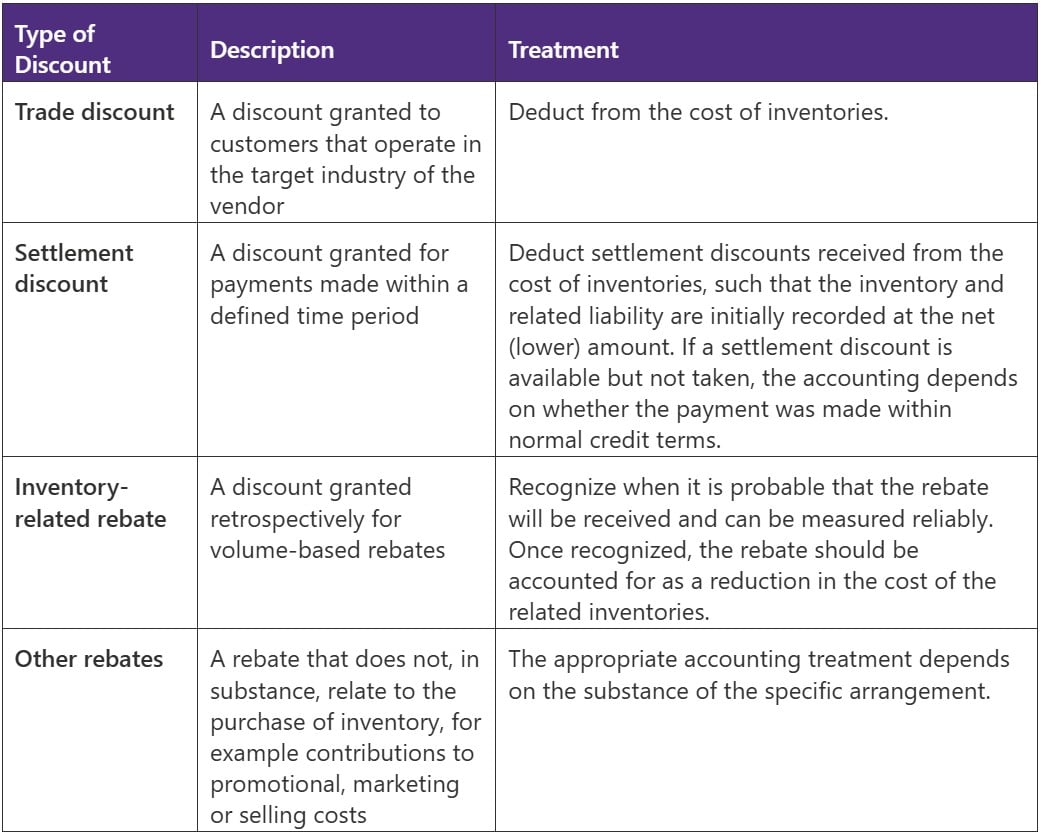
Discounts and rebates can be offered to purchasers in a number of ways, for example trade discounts, settlement discounts, volume-based rebates and other rebates. Accounting for these reductions will vary depending on the type of arrangement.Below is an overview of the accounting treatment of a variety of discounts:
Practical Impact
Entities should carefully evaluate supplier incentive arrangements to ensure rebates and discounts are accounted for in accordance with their economic substance. Particular attention should be given to:
- Judging whether payment terms contain a financing element;
- Estimating and monitoring the probability of achieving volume-based rebates;
- Assessing whether supplier payments relate to inventory purchases or separate goods and services; and
- Ensuring appropriate disclosure where significant judgments are involved.
Reference
The full publication is accessible and downloadable below.